Short-term rental insurance in Destin and Fort Walton Beach is built around three things: a policy written for short-term rental use that covers the home, contents, lost bookings, and liability; a plan for hurricane wind, either inside that policy with its own deductible or separately; and a flood policy for the Gulf, Choctawhatchee Bay, and Santa Rosa Sound. Condo owners add the association’s master policy and its rules to the picture.
The Emerald Coast Risk Profile
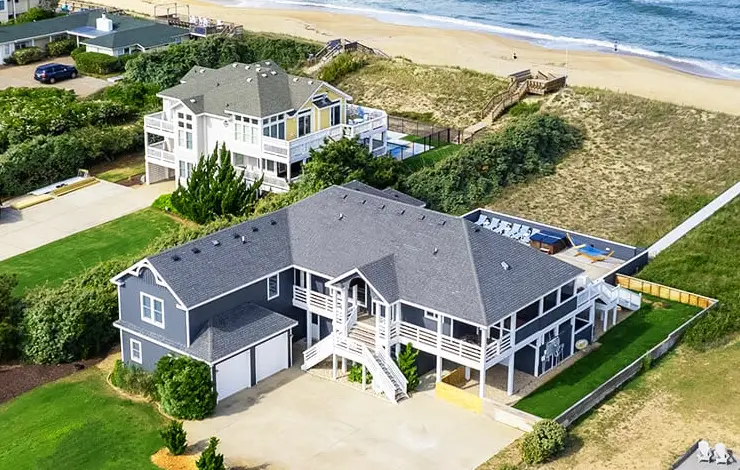
Destin, Fort Walton Beach, Okaloosa Island, and Miramar Beach rent hard from spring break through Labor Day, with family weeks, wedding groups, and fishing trips. The same stretch of coast sits in the Gulf’s hurricane path, with water on more than one side.
Hurricane Wind
Florida’s coastal wind market is tight, and the Panhandle is no exception. Some rental policies include wind with a separate hurricane deductible, which is often set as a share of the dwelling limit and can be much larger than the regular deductible. Others exclude wind, and the owner covers it separately.
Citizens Property Insurance Corporation, the state’s insurer of last resort, has eligibility rules about use and occupancy that can limit rental properties. Our post on Florida short-term rental insurance for wind, flood, and liability explains the state’s wind market, and our coastal rental guide explains how wind and named storm deductibles are triggered.
Insurers commonly stop binding new coverage when a storm threatens the Gulf. Make changes before the season. Our post on how soon short-term rental coverage starts covers binding moratoriums.
Flood
Flood is excluded from most property policies and covered by a separate flood policy. Beachfront homes, bayfront homes in Destin Harbor, and low-lying streets in Fort Walton Beach all carry flood exposure. Elevation drives the price. Buy it early, since federal policies generally carry a waiting period. Our flood insurance page explains the options.
Condos and Towers
Much of the Emerald Coast’s rental stock is in condo towers. The association’s master policy covers the building, and your unit policy covers your interior, contents, lost rent, and liability. Loss assessment coverage helps when a hurricane deductible is passed to owners. Our guide to Florida beach condo short-term rental insurance covers the details.
Liability for Groups
Destin draws groups: families sharing a house, wedding parties, and fishing trips. Larger groups mean more people on stairs, decks, and pool decks, and more chance of a late-night injury.
- Set occupancy limits and state them in the listing.
- Keep exterior stairs and decks on raised homes in good repair.
- Post pool rules and fit gates that close and latch on their own.
- Write rules on parties and visitors.
Golf carts, boats, kayaks, and paddleboards are popular here, and property liability policies commonly exclude motorized vehicles and watercraft. Ask your agent before you provide them. Our general liability coverage page covers the primary layer, our post on pool and hot tub liability covers the pool, and an umbrella adds limit.
Protecting the Summer
A storm in late summer, or a burst pipe in May, can take out the best weeks of the year. Loss of rents coverage pays lost booking income while covered damage is repaired. If wind is on a separate policy, check which policy pays lost rent after hurricane damage.
Scenario: The Golf Cart
A host in Miramar Beach leaves a golf cart for guests to drive to the beach. A guest backs the cart into a parked car and a pedestrian is knocked down. The host’s rental liability policy excludes motorized vehicles. The host has no coverage for the cart, and the pedestrian’s claim goes against the host directly. A golf cart policy, or a decision not to offer the cart, would have avoided the gap.
Licensing
Florida licenses vacation rentals through the Department of Business and Professional Regulation. Destin maintains its own short-term rental program on top of the state license, and Okaloosa County and other cities have their own rules and tourist tax registration. Associations add another layer. Our guide to short-term rental permits by state explains how they fit.
Construction and Mitigation Credits
Florida insurers give credits for features that reduce wind damage, such as roof-to-wall connections, impact-rated windows and doors, and newer roofs. A wind mitigation inspection documents those features. For a Destin or Fort Walton Beach rental, it can make a noticeable difference to the wind portion of the premium.
If you are buying, ask the seller for a recent wind mitigation report. If you own, consider having one done before renewal. Newer homes along the coast are often built to stronger standards than homes from earlier decades, and the report is how an insurer sees the difference.
Storm Plans and Guest Cancellations
A hurricane threat in July or August means canceled bookings, evacuations, and guests asking for refunds. Insurance does not usually pay for bookings lost because a storm was forecast. Loss of rents generally responds to covered physical damage, not to a cancellation before landfall.
Write a storm policy for your listing: when you will cancel, how refunds work, and what guests should do if an evacuation is ordered. Keep shutters or panels ready, and arrange someone local to secure the home. After the storm, photograph everything before cleanup begins.
An Emerald Coast Checklist
- Confirm state, city, and association rules.
- Get wind covered, and read the hurricane deductible.
- Buy flood early.
- Set loss of rents from summer income.
- Decide about golf carts and watercraft before offering them.
- Price an umbrella.
Our Florida page and beach house rental page cover more. For a quote, request a quote or call 317-942-0549.
Frequently Asked Questions
How do I insure a short-term rental in Destin?
With a policy written for short-term rental use that covers the home, contents, lost bookings, and liability, plus a plan for hurricane wind and a separate flood policy. Condo owners also need to understand the association’s master policy.
Is hurricane wind covered on a Destin rental policy?
Some policies include wind with a separate hurricane deductible, and some exclude it, leaving the owner to cover it separately. Ask which your quote does and what the hurricane deductible is.
Do Destin and Fort Walton Beach rentals need flood insurance?
Plan on it. Flood is excluded from most property policies, and homes near the Gulf, Choctawhatchee Bay, and Santa Rosa Sound all face storm surge and flooding. A separate flood policy is the only way to cover it.
Does Destin require a short-term rental license?
Florida licenses vacation rentals through the Department of Business and Professional Regulation, and Destin maintains its own short-term rental program on top of the state license. Okaloosa County and other cities have their own rules. Check each before listing.
Are golf carts and boats covered by my rental liability policy?
Often not. Property liability policies commonly exclude motorized vehicles and watercraft. If guests use a golf cart, a boat, or a paddleboard you provide, ask your agent how it is covered before offering it.
Does my policy cover lost summer bookings after a storm?
Loss of rents coverage pays lost booking income while covered damage is repaired. If wind is on a separate policy, check which policy pays lost rent after hurricane damage.
Can I get Citizens insurance for a Destin rental?
Citizens Property Insurance Corporation has eligibility rules about use and occupancy that can limit rental properties. Ask your agent whether it fits your property before relying on it.
The Bottom Line for Destin and Fort Walton Beach Hosts
Rentals on the Emerald Coast need a policy built for nightly guests, a clear plan for hurricane wind, and a separate flood policy, with loss of rents set to protect the summer. Licensing runs through the state, the city, and often the association, and each layer matters.
Read our Florida page and the beach house rental page, then submit a quote or call 317-942-0549.