Short-term rental insurance in Biloxi is usually built in pieces: a policy written for short-term rental use that covers the property and liability, a wind solution that may be inside that policy or bought separately, and a flood policy for storm surge and rising water. Hurricane wind is the hardest part to place on the Mississippi Gulf Coast, and the state’s windstorm underwriting association serves owners who cannot find wind coverage in the regular market.
Why the Gulf Coast Is Insured Differently
Biloxi, Gulfport, Ocean Springs, and Bay St. Louis sit on a coast that has seen major hurricane damage more than once. Insurers price for that history, and many limit how much wind exposure they take along the water. A policy that would be routine in Jackson or Oxford needs more structure here.
That structure usually has three parts.
Wind: Inside the Policy or Separate
Some insurers include wind on a Biloxi rental with a separate named storm or wind deductible. Others exclude wind, and the owner covers it separately. For properties that cannot find wind in the regular market, the Mississippi Windstorm Underwriting Association provides windstorm and hail coverage in the state’s coastal area. Its site describes the association and how to apply through an agent. Eligibility rules apply, so ask whether it fits a rental.
When wind is written separately, check that the two policies meet. The rental policy should exclude only what the wind policy covers, and the deductibles should be understood together.
The Wind Deductible
Coastal wind deductibles are often set as a share of the dwelling limit rather than a flat amount. On a higher-value home, that can be a large figure. Read it before storm season and set money aside for it. Our guide to coastal rental insurance for wind, named storms, and flood explains how these deductibles are triggered.
Flood and Storm Surge
Hurricane damage on this coast often comes from water as much as wind. Flood, including storm surge, is excluded from most property policies and covered by a separate flood policy. Buy it early, since federal policies generally carry a waiting period. Our flood insurance page and the post on flood insurance for short-term rentals cover how it works.
Disputes after a hurricane often turn on whether damage came from wind or water. Separate policies with clear boundaries, and photos of the property before the season, help.
Liability for Casino-Weekend Guests
Biloxi’s rental demand rides on the casinos, the beach, and events. Guests often come in groups, stay out late, and drink. That raises the chance of falls, fights, and damage.
- Set occupancy limits and state them in the listing.
- Write house rules about parties, visitors, and quiet hours.
- Keep exterior stairs and balconies on raised homes in good repair.
- Light walkways and parking areas.
Our general liability coverage page covers the primary layer, and an umbrella adds limit. Our post on the liquor liability exclusion explains how alcohol-related claims are treated.
Local Rules
Mississippi has no statewide short-term rental registration program. Biloxi, Gulfport, and other coastal cities set their own permit and zoning rules. Check with the city before listing. Our guide to short-term rental permits by state explains how to find the right office.
Scenario: Wind on One Policy, Water on Another
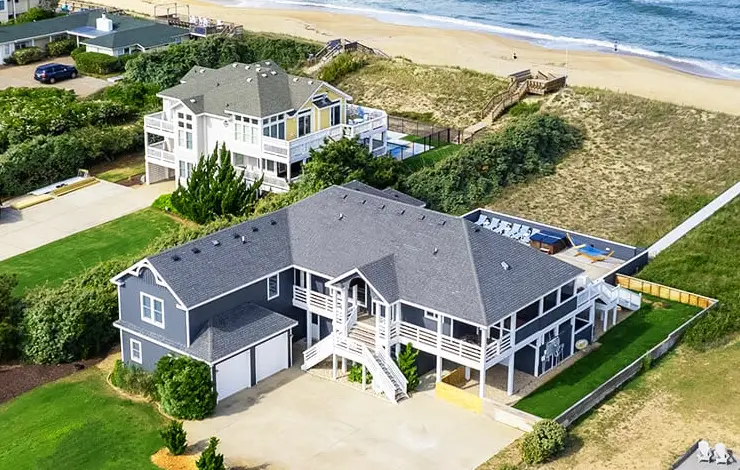
A host owns a raised beach house in Biloxi with a rental policy that excludes wind, a separate wind policy, and a flood policy. A hurricane makes landfall nearby. The roof loses shingles and a window breaks, letting rain into the upper floor, and storm surge floods the ground-level storage and stairs. The wind policy handles the roof and window after its deductible. The flood policy handles the ground-level damage. The rental policy’s loss of rents coverage is checked against the wind exclusion. Each adjuster asks for the pre-season photos the host took in May.
Raised Homes and Building Codes
Many Gulf Coast homes were rebuilt or raised after past hurricanes, and newer construction is generally built to stronger wind and flood standards. That matters for insurance. A raised home built to current code usually prices better for both wind and flood than an older home at grade.
Keep the documents that prove it: the elevation certificate, the permit and inspection records for the rebuild, and invoices for roofing, windows, and shutters. When you request a quote, send them. Mitigation features only lower the price if the insurer knows about them.
Comparing Gulf Coast Quotes
Because Biloxi coverage comes in pieces, quotes can be hard to compare. Ask each agent to show the full program in one table: the rental policy, the wind policy if separate, the flood policy, and any umbrella, with each premium and each deductible.
Look especially at the wind deductible, which can be the largest out-of-pocket cost after a storm. A lower premium with a much larger wind deductible is not always the better choice. Our guide to the national cost picture explains the general drivers of short-term rental premiums.
The Off Season
Biloxi rentals see steady casino traffic but quieter months too. A home empty for weeks can suffer an unnoticed leak or break-in. Ask how your policy treats vacancy, arrange regular checks, and fit leak and temperature sensors so problems surface quickly.
Before Hurricane Season
The Mississippi Insurance Department publishes a consumer hurricane checklist for property owners. For hosts, add:
- Confirm wind, flood, and the rental policy are all in force.
- Write down every deductible.
- Photograph the property inside and out.
- Check loss of rents and which policy pays it after wind damage.
- Plan how you will cancel or move guests if a storm approaches.
Insurers commonly stop binding new coverage when a storm threatens, so make changes early. Our post on how soon short-term rental coverage starts explains binding moratoriums.
Our Mississippi page and beach house rental page cover more. For a Biloxi quote, request a quote or call 317-942-0549.
Frequently Asked Questions
Is short-term rental insurance hard to get in Biloxi?
It takes more work than inland Mississippi. Fewer insurers write hurricane wind on the Gulf Coast, and those that do often set large wind deductibles. It is available, but expect a longer quote process and a policy built in pieces.
What is the Mississippi Windstorm Underwriting Association?
It is the state’s residual market for windstorm and hail coverage in the coastal area of Mississippi, for property owners who cannot find wind coverage in the regular market. Eligibility rules apply, so ask your agent whether it fits a rental.
Do I need flood insurance for a Biloxi rental?
Plan on it. Flood is excluded from most property policies, and storm surge is a major risk along the Mississippi coast. A separate flood policy is the only way to cover it.
Does Biloxi require a permit for short-term rentals?
Mississippi has no statewide short-term rental registration program. Cities such as Biloxi and Gulfport set their own permit and zoning rules. Check with the city before listing.
Does casino traffic affect my rental’s liability?
Larger groups, late nights, and alcohol raise liability exposure. Clear house rules, occupancy limits, and a liability policy that fits the property help. An umbrella adds limit for serious claims.
How does a hurricane deductible work in Mississippi?
Coastal policies often carry a separate named storm or wind deductible, commonly set as a share of the dwelling limit. It applies when a storm meets the policy’s definition and can be much larger than the regular deductible.
Will a policy cover lost bookings after a hurricane?
Loss of rents coverage pays lost booking income while covered damage is repaired. If wind is on a separate policy, check which policy pays lost rent after wind damage, since it may need to be on both.
The Bottom Line for Biloxi Hosts
A Biloxi rental is usually insured in pieces: a rental policy for property and liability, a wind solution that may come from a separate policy or the state’s wind pool, and a flood policy. Get the pieces to meet, read the wind deductible, and protect the booking income.
Read our Mississippi page, then submit a quote or call 317-942-0549.