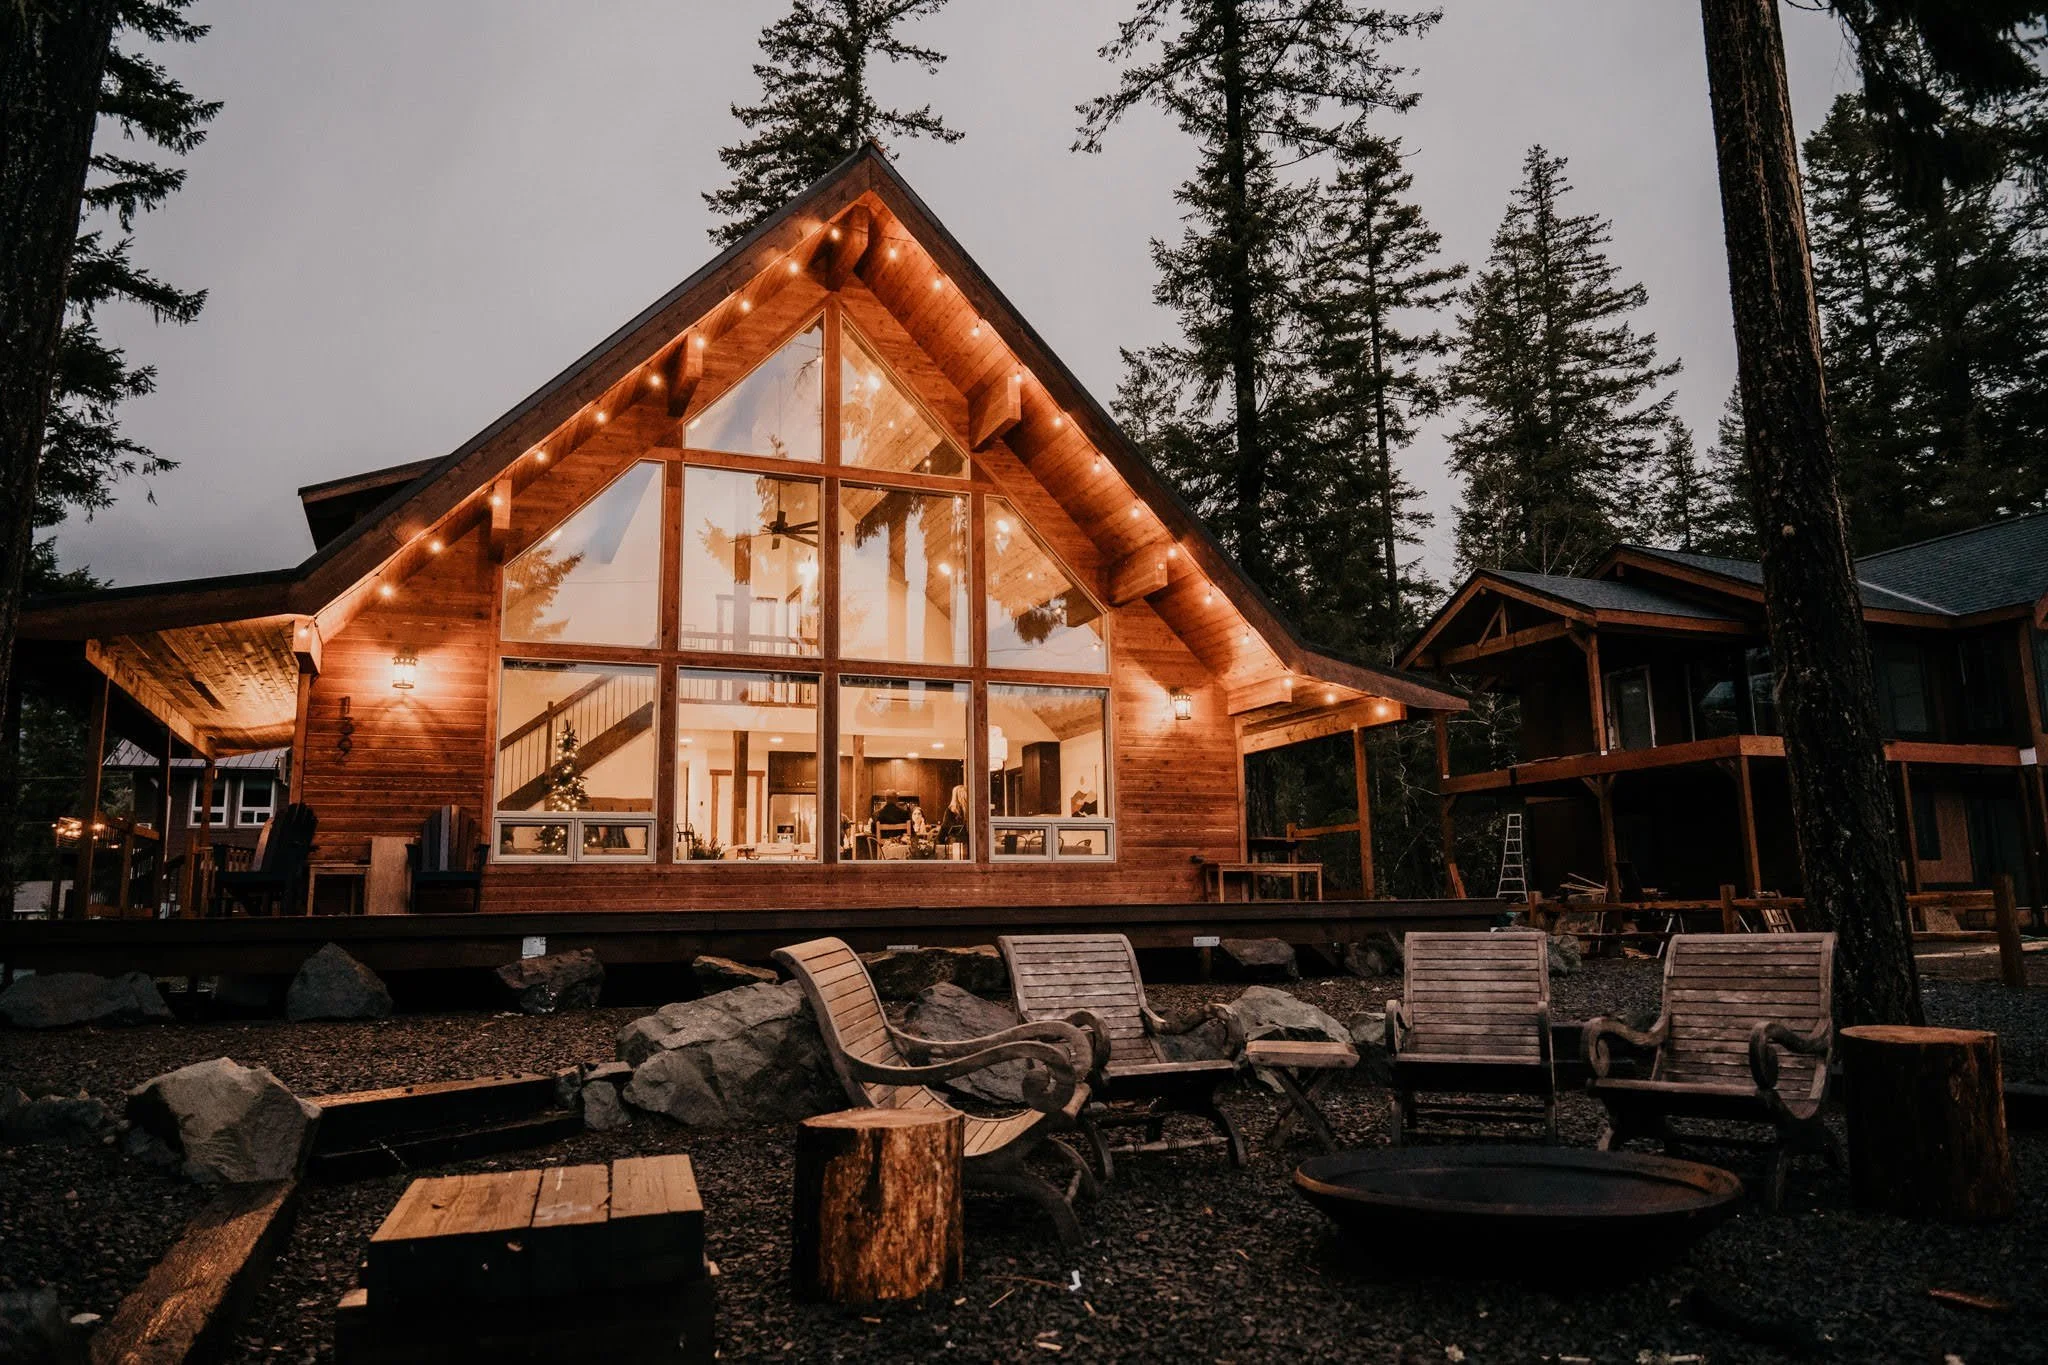
Luxury vacation rental insurance for high-value furnishings comes down to contents coverage: the overall contents limit, the sublimits for categories like art and electronics, the valuation basis, and how the policy treats theft or damage by guests. A standard rental policy may carry enough contents limit for ordinary furniture and still fall short for designer pieces, artwork, or a full entertainment system. Items above what the form handles are scheduled separately or kept out of the rental.
Why Luxury Rentals Need a Closer Look
Most short-term rental policies were built around ordinary furnishings: beds, sofas, dining sets, linens, kitchenware, a few televisions. A luxury home is furnished to a different standard. Custom upholstery, imported lighting, original art, wine storage, and integrated audio and video systems can add up quickly.
Two problems follow. The contents limit may be too low for the total, and the sublimits may be too low for specific categories even when the total looks fine. Our contents coverage page explains how contents coverage is structured on rental policies.
Limits, Sublimits, and Valuation
The overall limit. Add up what it would cost to refurnish the home today, room by room, at the standard the listing promises. That is your starting point.
Sublimits. Read the contents section for categories with their own caps. Art, jewelry, collectibles, and electronics are common. A sublimit applies even when the overall limit has room.
Valuation. Replacement cost pays for new items of like kind and quality. Actual cash value deducts depreciation. A luxury sofa a few years old can pay out very differently under the two. Ask which one your policy uses for contents.
Guest Theft and Damage
At a luxury rental, the guest is often the biggest variable. Some rental policies cover theft by guests. Others limit it or exclude it, sometimes because a homeowners-style form excludes theft by people you invited in. This is the question to ask first.
Accidental damage is usually more straightforward if the policy covers contents. Intentional damage may be treated as vandalism or excluded. Read how your policy defines each.
Platform programs add a layer for platform bookings. Airbnb’s host damage protection has its own terms and documentation rules, set out in its help article on host damage protection, and does not apply to direct bookings. Our comparison of guest damage protection deductibles and limits shows how the layers stack.
Scheduling What the Form Cannot Carry
For pieces worth more than a sublimit allows, there are three options:
- Schedule the item on the rental policy, if the insurer offers it, often at an agreed value supported by an appraisal.
- Buy a separate fine art or valuables policy that accepts the rental setting. Not all of them do, so confirm in writing.
- Keep it out of the rental. Irreplaceable pieces are safest in a locked owner’s closet or another home.
An appraisal is usually required for agreed-value scheduling. Keep it current, since values move.
The Building Matters Too
Luxury homes often have custom finishes, specialty materials, and systems that cost more to repair than standard construction. Check that the dwelling limit reflects true rebuild cost. Ask about ordinance and law coverage if the home is older, and equipment breakdown coverage for pool equipment, generators, and smart-home systems.
Liability rises with the property. A luxury home often comes with a pool, a hot tub, high group capacity, and event inquiries. An umbrella policy is common at this level, and our post on pool and hot tub liability lists what insurers ask.
Scenario: The Sculpture and the Sublimit
A host furnishes a hillside rental with original art, including a bronze sculpture on the terrace. The policy has a generous contents limit, and the host assumes it covers everything. During a stay, a guest backs into the sculpture’s pedestal while moving furniture for a photo, and it falls and breaks. The claim is covered, but the policy’s fine art sublimit pays a fraction of the sculpture’s appraised value. The host schedules the remaining pieces at agreed value the following week.
Keep an Inventory
An inventory turns a claim from an argument into a list. Include photos of each room and each significant item, receipts or appraisals, serial numbers for electronics, and the date each item was bought. Store it outside the property. Update it at each refresh.
Our essential furniture checklist for Airbnb hosts is a starting point for the room-by-room list.
Valuing the Contents Correctly
Most hosts underestimate contents. They remember the big purchases and forget the rest: the linens for every bed, the kitchen equipment, the outdoor furniture, the lighting, the rugs, the décor. In a luxury home, those smaller items are also higher quality and cost more to replace.
Walk the house room by room with your inventory and price what it would cost to replace each item today, at the same quality. Include outdoor furnishings, game rooms, and anything in storage for the property. Then compare the total with the contents limit on your policy. If the inventory is much larger than the limit, raise the limit or schedule the high-value items.
Security and Access
A luxury home attracts attention, and how you control access affects both theft risk and how insurers view the property. Smart locks with a unique code for each stay, exterior cameras where local law and platform rules allow, and a locked owner’s closet all help.
Be careful with interior cameras. Platforms restrict them and guests object to them. Exterior cameras pointed at entrances and driveways, disclosed in the listing, are the usual approach. Our post on five safeguards that lower short-term rental insurance risk covers access control and other measures insurers like to see.
Before the Next Booking
- Add up the replacement cost of the furnishings.
- Read every contents sublimit.
- Confirm replacement cost valuation.
- Ask how guest theft is treated.
- Schedule or remove anything the form cannot carry.
Luxury properties are common in our single-family and beach house placements. For a contents review, request a quote and send the inventory. The Triple-I guide to renting out your home explains why rental use needs coverage built for it.
Frequently Asked Questions
Does short-term rental insurance cover expensive furniture?
It can, through contents coverage, if the policy includes it and the limit is high enough. Some policies set sublimits for art, electronics, or other categories below the overall contents limit. Read the contents section and the sublimits before relying on it.
What is the difference between replacement cost and actual cash value for furnishings?
Replacement cost pays to replace an item with a new one of like kind and quality. Actual cash value subtracts depreciation, so an older sofa pays out less. For a luxury rental, the valuation basis can change a payout more than the limit does.
How do I insure artwork in a vacation rental?
Ask whether the rental policy covers fine art and at what limit. For valuable pieces, an agreed-value schedule on the policy or a separate fine art policy that accepts rental use may fit better. Keep appraisals and photos current.
Are guests’ thefts of my belongings covered?
Some rental policies cover theft by guests and some limit or exclude it. This is one of the most important questions for a luxury host. Ask your agent directly and get the answer in writing.
Does AirCover reimburse for high-value items a guest damages?
Airbnb’s host damage protection has its own terms, exclusions, and documentation rules, and it applies only to Airbnb bookings. Read the program terms in Airbnb’s Help Center, and carry your own contents coverage for the rest.
How do I prove the value of furnishings after a loss?
Keep an inventory with photos, receipts, appraisals, and serial numbers, stored somewhere outside the property. Update it when you buy or replace something. A clear inventory is the fastest route to a fair settlement.
Should I keep the best pieces out of the rental?
Many luxury hosts lock irreplaceable items in an owner’s closet or keep them elsewhere. Items that cannot be replaced at any price are better protected by not putting them in front of guests at all.
The Bottom Line on Insuring Luxury Furnishings
In a luxury vacation rental, the contents can be worth as much attention as the building. Check the contents limit, every sublimit, the valuation basis, and how guest theft is treated, then schedule anything the standard form cannot carry. An inventory makes every claim easier.
Read our contents coverage page, then submit a quote or call 317-942-0549 with your inventory.