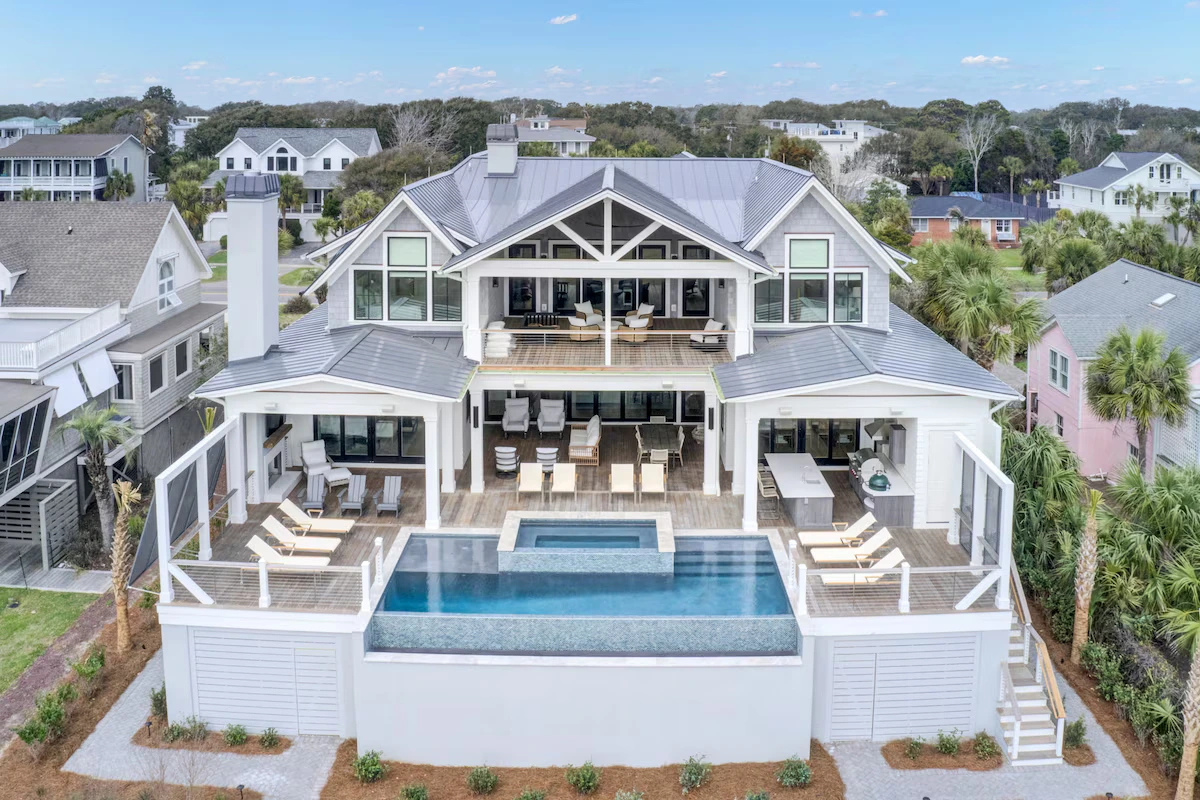
Jersey Shore rental insurance cost depends on how close the home sits to the ocean and how high it sits above the flood line. Short-term rental insurance varies, but it ranges from $700 annually for smaller rentals to over $3,000 for larger dwellings. Barrier-island homes on Long Beach Island, the Wildwoods, and Ocean City tend to land toward the top of that range or above it, especially once a separate flood policy is added. Mainland homes a few miles inland tend to land lower.
What the Number Includes
The range covers the short-term rental policy: property and liability coverage written for nightly or weekly guests. At the shore, two items usually sit beside it:
- A flood policy, bought separately from the federal program or a private flood insurer.
- An umbrella, often added for homes with pools or large group capacity.
Compare quotes piece by piece. A policy that looks inexpensive may carry a large wind deductible or leave out coverage another quote includes.
Barrier Island Versus Mainland
Barrier-island homes take wind from the ocean and flooding from both sides. Lagoon-front homes behind the islands avoid direct surf but flood in back-bay surges and high tides. Mainland homes in towns like Toms River or Manahawkin face less of both. Insurers price those differences into every quote.
The Factors That Move the Price
Elevation. For flood, the height of the lowest floor above the expected flood level is one of the largest pricing factors. Many shore homes were raised after past storms. An elevation certificate documents the height and helps the flood quote.
Construction and roof. Newer construction built to modern coastal codes, impact-rated openings, and a newer roof lower wind risk.
Size and value. A large oceanfront home with a high rebuild cost costs more to insure than a small bungalow. Shore rebuild costs run high because labor and materials have to reach the island.
Wind deductible. Coastal policies often carry a separate wind or named storm deductible, sometimes set as a share of the dwelling limit. A higher one lowers premium and raises what you pay after a storm.
Amenities and capacity. Pools, roof decks, and large group capacity add to the liability side. Our post on pool and hot tub liability covers what insurers ask.
Protect the Summer
Shore rentals earn most of their income from Memorial Day to Labor Day. A pipe burst in April or a kitchen fire in June can take out a season’s bookings. Loss of rents coverage pays lost booking income while covered damage is repaired. Set the limit from the summer income, not an annual average spread across empty months. Our post on the twelve-month loss of rents cap explains how the time limit works.
Local Rules
Many shore municipalities run their own rental registration, inspection, or permit programs, and they differ town to town. Some require annual inspections or posted occupancy limits. A rental that meets local rules is easier to insure and easier to defend after a claim. The New Jersey Department of Banking and Insurance home insurance basics page covers state consumer rules for property policies.
Scenario: The Same Street, Two Quotes
Two owners on the same Long Beach Island street request quotes in the same week. One home was raised and rebuilt to current code, with an elevation certificate and a newer roof. The other sits at grade with an older roof. Both are similar in size. The raised home’s flood policy costs far less, and its wind terms are better. The owner of the older home asks what elevating would change and starts pricing the project.
Nor’easters and Winter
Hurricanes get the attention, but the Jersey Shore also takes nor’easters, which can bring days of wind, high tides, and flooding in fall and winter. Shore rentals are often empty in those months, and an empty house can suffer water damage that goes unnoticed for days.
Winterize the home if it sits empty: shut off and drain the water or keep the heat at a safe level, and arrange regular checks. Some policies limit coverage for freeze damage or vandalism in a vacant home. Ask how your policy treats long gaps between bookings, since a shore rental may sit empty for most of the off season.
Comparing Quotes Fairly
Shore quotes vary widely, and the cheapest is not always the better buy. Line them up on the same terms:
- Dwelling limit, and whether it reflects true rebuild cost on the island.
- All-peril deductible and wind deductible, including whether the wind deductible is a flat amount or a share of the limit.
- Loss of rents, and how long it pays.
- Liability limit, and whether pools and decks are covered without restriction.
- What is excluded, especially wind or water.
A quote that looks inexpensive because it carries a large wind deductible may cost more after one storm than a higher premium would have over several years.
Owner Use Outside the Season
Many shore owners use the house themselves in spring and fall and rent it all summer. Tell your agent how much the family uses it. Some rental policies allow owner occupancy and some are written for rental-only use, and the difference matters if something happens during a family weekend.
Ways to Lower the Cost
- Get an elevation certificate if you do not have one.
- Upgrade the roof and openings.
- Choose deductibles deliberately, including the wind deductible.
- Keep values accurate.
- Combine several shore rentals on one policy if you own them. See insuring multiple rentals under one policy.
Our beach house rental page covers how coastal homes are written, and our flood insurance page covers the separate flood layer. For a number on your shore rental, request a quote or call 317-942-0549.
Frequently Asked Questions
How much does short-term rental insurance cost at the Jersey Shore?
Short-term rental insurance varies, but it ranges from $700 annually for smaller rentals to over $3,000 for larger dwellings. At the Jersey Shore, barrier-island location, elevation, flood, and the size of the home decide where a rental falls, and oceanfront homes can run above that.
Is flood insurance included in a Jersey Shore rental policy?
Usually not. Flood is excluded from most property policies and bought separately. Barrier-island homes are among the most flood-exposed properties in the state, so plan on a separate flood policy.
Why do Jersey Shore rentals cost more to insure than inland ones?
Coastal storms, storm surge, and wind drive most of the difference. Homes on barrier islands such as Long Beach Island face more of all three than a home on the mainland a few miles inland.
Does elevation lower Jersey Shore insurance?
Elevation is one of the biggest factors in flood pricing, and a home raised above the expected flood level is generally cheaper to insure for flood than one at grade. An elevation certificate documents it.
Do I need loss of rents coverage for a summer-only rental?
It is worth pricing. Shore rentals earn most of their income in a short season, so damage in late spring can wipe out the year’s bookings. Make sure the limit reflects the summer income, not an average month.
Do Jersey Shore towns require rental registration?
Many shore municipalities run their own rental registration, inspection, or permit programs. Rules differ from town to town. Check with the municipality before your first booking each season.
How can I lower my Jersey Shore rental insurance cost?
Elevating the home, upgrading the roof and openings, choosing a higher deductible, and keeping a clean claims record all help. Accurate values and an elevation certificate help the flood side.
The Bottom Line on Jersey Shore Rental Insurance Cost
Short-term rental insurance ranges from $700 a year for smaller rentals to over $3,000 for larger dwellings, and at the Jersey Shore the location, elevation, and flood policy decide where a rental lands. Budget for flood as its own line and protect the summer income with loss of rents.
Read our New Jersey page, then submit a quote or call 317-942-0549 for a figure on your shore rental.