If you rent out your vacation home fewer than 100 nights a year, the insurance question is whether your current second-home policy accepts any paid stays at all, because many personal policies limit or exclude rental activity regardless of how few nights it covers. The answer comes from your own insurer, not from a night count. If your insurer allows only a narrow endorsement, a policy written for short-term rental use that also allows owner occupancy often fits better.
The Second Home Between Two Policies
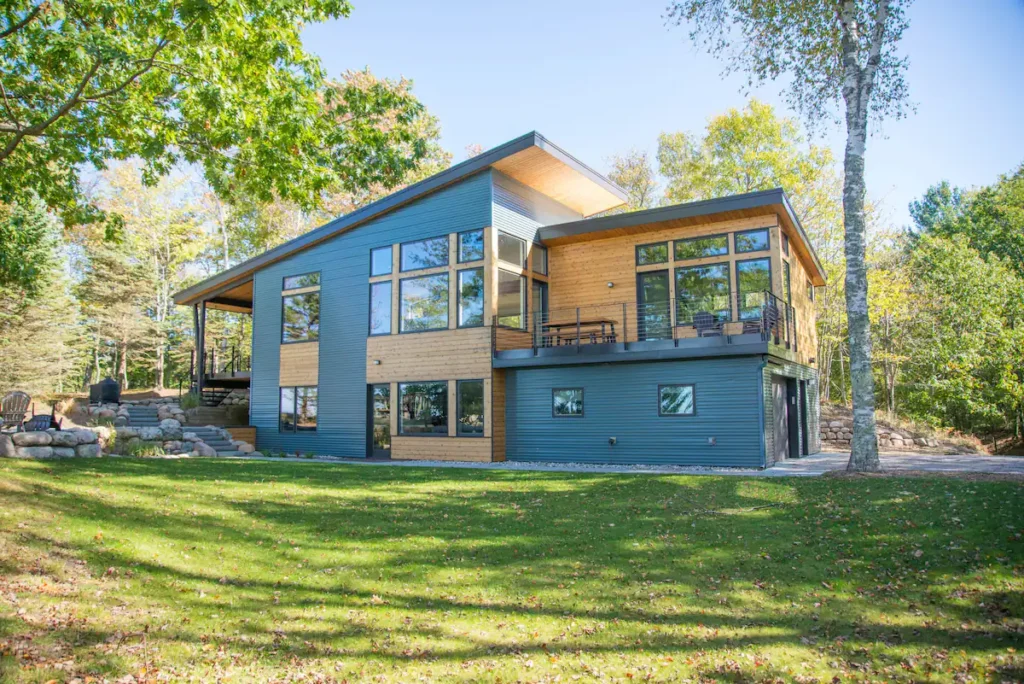
A family lake house, beach cottage, or mountain cabin often starts on a seasonal or secondary homeowners policy. Those policies are written for the family’s own use. Renting the home to paying guests, even for a few weeks around holidays, can move it into territory the policy was not built for.
Insurers handle this differently. Some allow a small amount of rental use. Some offer an endorsement. Some treat any paid stay as business use and exclude it. There is no universal threshold, which is why the same rental pattern can be fine with one insurer and uncovered with another.
The NAIC’s guidance on home-sharing gives the same advice: tell your insurer before you rent, and find out what your policy covers.
Three Ways to Insure a Part-Time Rental
A personal policy that allows limited rental. This works only if the insurer says so in writing. Ask what counts as rental, whether there is a cap, and whether liability and property both apply during a stay.
A personal policy with an endorsement. Endorsements vary. Some extend liability only. Some cap the number of days or the number of rentals. Some exclude theft or damage by renters. Read the endorsement itself, not a summary.
A short-term rental policy that allows owner use. Built for paying guests from the first night. Many allow the owner to use the home between bookings, but some are written for rental-only use. Confirm that your own stays are covered.
Questions to Ask Your Current Insurer
- Does my policy allow any rental use, and if so, how much?
- Is there an endorsement, and what does it limit?
- Does liability apply to paying guests?
- Is theft or damage by a guest covered?
- Does loss of rental income apply if the home is damaged?
- What happens if I rent more next year?
Write down the answers, and ask for the key ones in writing.
When the Endorsement Is Not Enough
An endorsement can be the right answer for a home rented a handful of times. It tends to fall short when:
- Bookings come through a platform on a regular calendar
- The home has a pool, a dock, or a hot tub
- You want loss of rents coverage for booked weeks lost to a covered loss
- The endorsement excludes guest theft or caps rental days below your plan
At that point, a policy built for the use you have is usually cleaner. Our post on short-term rental insurance versus landlord insurance explains why nightly guests need their own form.
Your Own Use Still Counts
A part-time rental is also your family’s vacation home. Your coverage needs to work when you are there too. Tell your agent roughly how many nights the family uses the home and whether you keep personal items locked away during rentals. Those details affect how contents coverage and liability are written.
Our page on owner-occupied short-term rental insurance covers homes where the owner lives on site. A seasonal second home is a different arrangement, and cabin and mountain rentals are often written this way.
Scenario: The Holiday Weeks
A family owns a lake cottage on a seasonal homeowners policy and rents it out for the two busiest weeks each summer to cover taxes. They never told their insurer. During one of those weeks, a guest leaves a burner on and a kitchen fire spreads to the cabinets. The adjuster learns the home was rented and points to the policy’s business activity exclusion. A rental endorsement or a short-term rental policy, either one placed before the summer, would have changed the outcome.
Taxes and Local Rules
Renting even part of the year can create tax and permit obligations. Tax treatment is a question for your accountant. Local short-term rental rules vary by town, and some apply from the first night. Our guide to short-term rental permits by state explains how to find the right office.
Your Belongings and the Guests’
A family vacation home is full of family belongings: clothes in the closets, photos on the walls, the kids’ games, the fishing gear. When you rent it, those things are within reach of strangers.
Decide what stays and what goes into a locked owner’s closet. Then tell your agent how the contents are used. Some rental policies cover the owner’s furnishings that guests use but treat personal items differently. If you keep valuable personal property at the home, ask whether it is covered during rental periods.
Guests bring their own belongings too. Your property policy generally does not cover a guest’s luggage, and your liability coverage applies only if you are legally responsible for the loss. Say so in the house rules.
When Friends Stay for Free
Many part-time hosts lend the house to friends and relatives between paid stays. That use matters to an insurer as well. A friend who stays free is not a paying guest, but they are not you either. Ask your agent how the policy treats non-paying guests when you are not there, especially if they bring their own friends.
A simple rule helps: keep a calendar of every stay, paid or not, with who was there. If something happens, you can show exactly how the home was being used that week.
Before You Rent It Out
- Call your insurer and describe the rental plan.
- Get the answer in writing.
- Read any endorsement in full.
- Compare it with a short-term rental policy that allows owner use.
- Disclose amenities and changes.
For a side-by-side comparison, request a quote or call 317-942-0549.
Frequently Asked Questions
Do I need special insurance if I rent my vacation home a few weeks a year?
Usually, yes. A second-home or seasonal homeowners policy is written for personal use, and many limit or exclude rental activity. Even part-time renting can trigger that limit. Ask your insurer how it treats rentals at your level and get the answer in writing.
Is there a number of rental nights that changes my insurance?
Each insurer sets its own threshold, and some have none, treating any paid stay as business use. There is no universal cutoff. That is why the question has to go to your own insurer with your actual rental pattern.
What is a home-sharing or rental endorsement?
It is an add-on to a homeowners or dwelling policy that extends some coverage to occasional rental use. Endorsements vary widely. Some cover liability only, some limit the number of rental days, and some exclude certain losses during a rental.
Is a short-term rental policy overkill for a part-time rental?
Not necessarily. A policy built for short-term rental use is designed for paying guests from the first night. For a home rented on a regular schedule, even part of the year, it often fits better than stretching a personal policy with endorsements.
Does my coverage change when I am staying at the home myself?
It can. Some rental policies are written for rental-only use, and others allow owner occupancy between bookings. Tell your agent how many nights you and your family use the home so the policy covers both uses.
Will Airbnb or VRBO protection cover a part-time host?
Platform programs apply to stays booked on the platform, under its terms, regardless of how often you rent. They do not cover your own family’s use, direct bookings, or the building against non-guest perils. They are a backstop, not the base policy.
What happens if my insurer finds out I was renting without telling them?
A claim tied to the rental may be denied, and the insurer may cancel or non-renew the policy. Disclosing the rental upfront is almost always cheaper than discovering the gap after a loss.
The Bottom Line on Insuring a Part-Time Rental
A vacation home rented out only some of the year still needs coverage that accepts paying guests. Start by asking your current insurer how it treats your rental pattern. If the answer is an endorsement with tight limits, compare it with a policy built for short-term rental use and owner use together.
Read our vacation rental insurance page, then submit a quote or call 317-942-0549 with your rental calendar.